
Managing rental property finances involves more than collecting rent and paying expenses. As a landlord, you may occasionally use personal funds to cover property costs or transfer money from your rental business into your personal bank account.
These transactions are known as owner contributions and owner withdrawals, and tracking them correctly is essential for maintaining accurate financial records.
When these transactions are incorrectly categorized as rental income or operating expenses, they can distort your property's profitability, cash flow reports, and financial statements.
In this guide, we'll explain what owner contributions and withdrawals are, how they affect your rental property accounting, and how to track them properly.
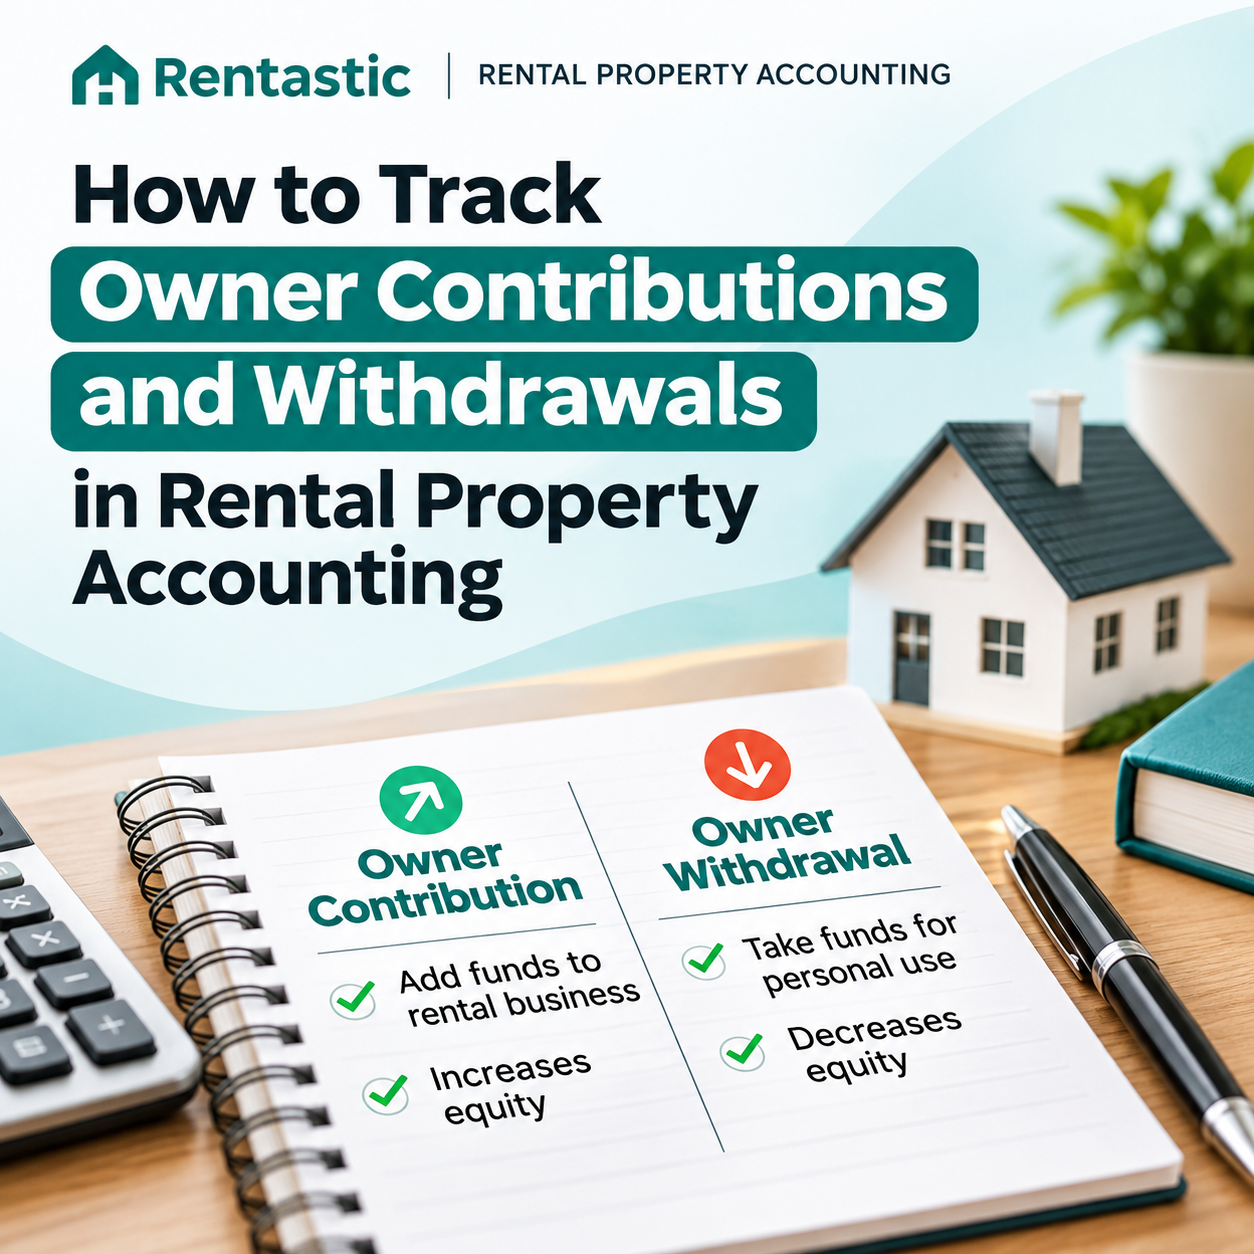
An owner contribution occurs when a property owner puts personal money or other assets into their rental property business.
This typically happens when the rental business needs additional funds to cover expenses, make improvements, or maintain sufficient cash reserves.
Common examples include:
No. Owner contributions are generally not considered rental income.
For example, suppose your rental property generates $2,000 in monthly rent, and you transfer another $3,000 from your personal savings into its bank account.
Your bank account receives $5,000, but your actual rental income is still only $2,000.
The additional $3,000 represents money contributed by the owner rather than revenue generated by the property.
Recording the entire $5,000 as rental income would significantly overstate your property's earnings.
An owner withdrawal, sometimes called an owner's draw or distribution, occurs when a property owner takes money out of the rental business for personal use.
These transactions are common among landlords who periodically transfer rental profits into their personal accounts.
Examples include:
Generally, no.
Owner withdrawals are not operating expenses because they do not represent costs incurred to maintain or operate the rental property.
Consider this example:
Your rental property earns $2,500 in rent and incurs $1,200 in operating expenses.
That leaves $1,300 in operating profit before other items such as financing costs.
If you withdraw $800 for personal use, that withdrawal does not create another $800 operating expense.
Instead, it reduces the cash available in the rental business.
The key distinction: Owner withdrawals affect your available cash and ownership accounts, but they do not directly reduce your rental property's operating profit.
Although both involve transferring money between the owner and the rental business, they serve opposite purposes.
For a sole proprietor or single-member LLC using equity accounting, these transactions are typically recorded through owner equity accounts. Partnerships and corporations may use different capital, distribution, or shareholder accounts depending on their legal and tax structure.
Accurate bookkeeping starts with separating rental business activity from personal financial transactions.
Here's how to handle both situations.
Your accounting system should distinguish between rental income, operating expenses, and owner-related transfers.
Consider using categories such as:
The exact account names depend on your business structure and accounting software.
Keeping these transactions separate prevents personal transfers from being mistaken for rental income or deductible expenses.
Suppose you transfer $4,000 from your personal checking account into your rental business account to fund upcoming repairs.
For a contribution treated as equity, the bookkeeping entry would generally be:
Debit: Cash — $4,000
Credit: Owner Contributions / Equity — $4,000
This increases the business's cash and owner equity without increasing rental income.
If the money is intended to be repaid as a loan rather than contributed as equity, it should generally be recorded as a liability instead.
Now suppose you transfer $1,000 from your rental business account to your personal account.
For an owner's draw, the entry would generally be:
Debit: Owner Draws / Distributions — $1,000
Credit: Cash — $1,000
This reduces the rental business's cash and owner equity without recording an operating expense.
Remember that the accounting treatment of distributions can vary depending on whether the property is owned individually, through a partnership, LLC, or corporation.
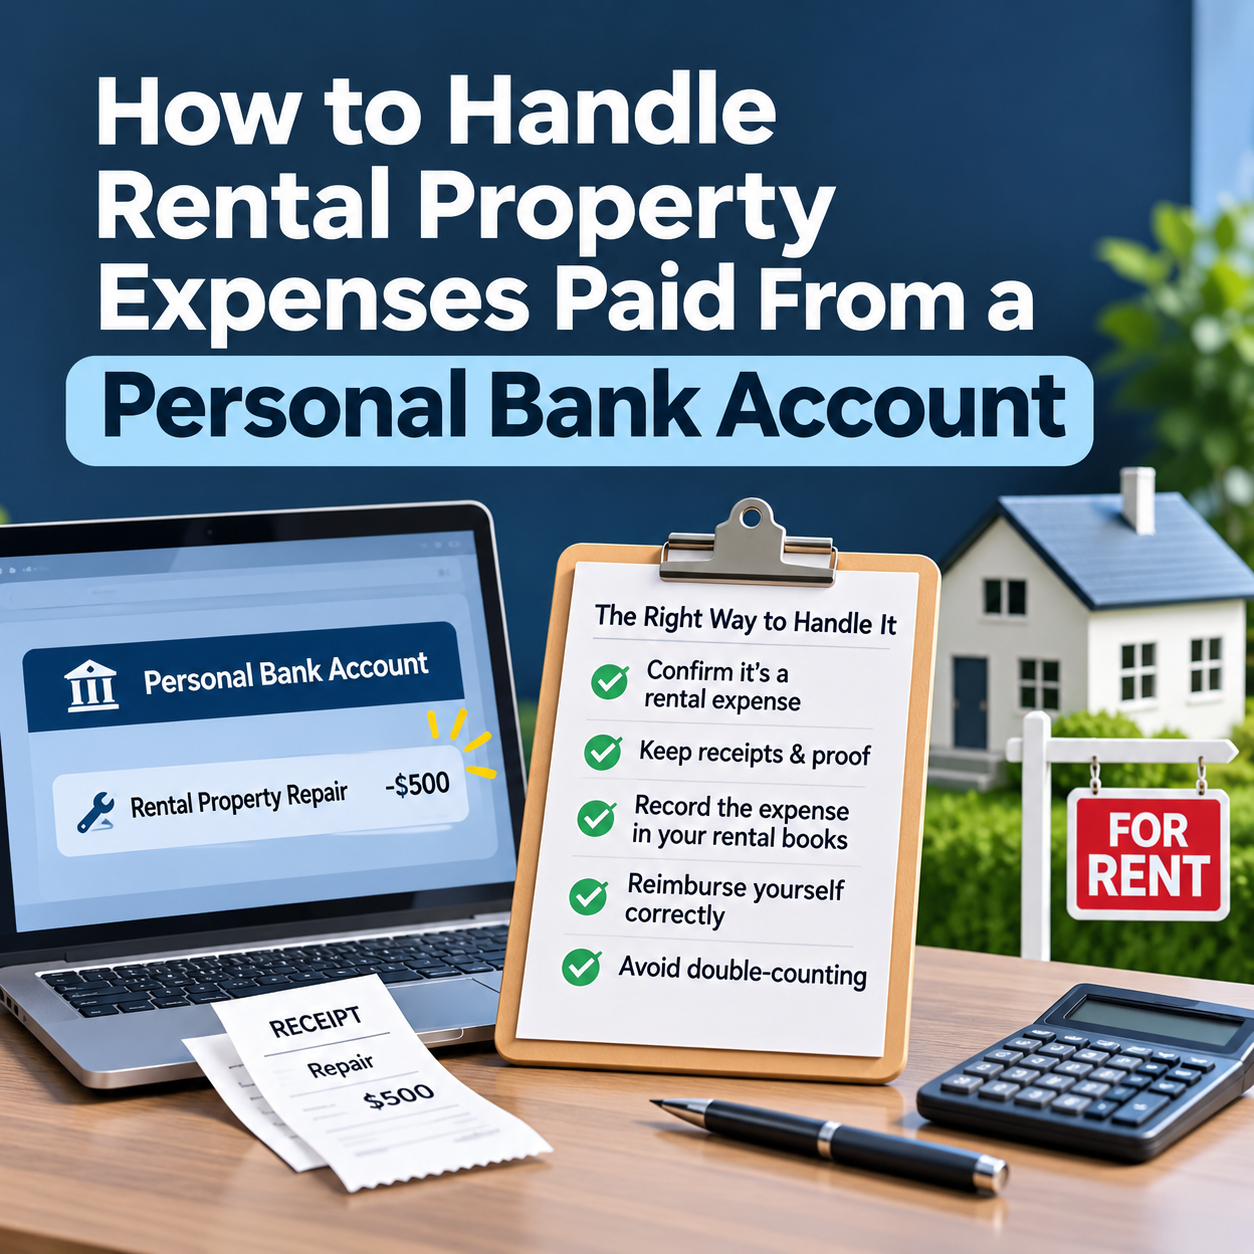
Sometimes landlords pay legitimate rental expenses directly from their personal accounts.
For example, you might use a personal credit card to purchase $350 worth of plumbing materials for your rental property.
The expense should still be recorded as a rental expense if it qualifies as such.
Depending on the circumstances, the offsetting entry may be recorded as an owner contribution or an amount payable to the owner.
For example, if treated as a contribution:
Debit: Repairs and Maintenance — $350
Credit: Owner Contributions / Equity — $350
This allows the rental property expense to appear in your financial records without incorrectly showing a payment from the rental business bank account.
Keep the receipt and document which property benefited from the purchase.
Imagine a landlord has the following transactions during one month.
The rental property's operating profit is:
$3,000 − $1,400 = $1,600
The owner contribution and withdrawal do not change this $1,600 operating profit.
However, assuming all transactions pass through the business bank account, the net cash increase is:
$3,000 − $1,400 + $2,000 − $800 = $2,800
This illustrates why rental property profit and changes in your bank balance are not always the same.
Your rental property generated $1,600 in operating profit, but its cash balance increased by $2,800 because of owner-related transactions.
Note: This simplified example excludes mortgage principal, depreciation, taxes, and other potential adjustments.
Even experienced property owners can make bookkeeping mistakes when personal and rental finances overlap.
Depositing personal funds into your rental account does not mean your property earned additional revenue.
Doing so can inflate reported rental income and create misleading financial reports.
Better approach: Record qualifying contributions under an appropriate equity account rather than rental income.
An owner's draw is not the same as paying for repairs, insurance, utilities, or property management.
Treating personal withdrawals as operating expenses can make a profitable rental appear less profitable than it actually is.
Better approach: Use a separate owner draw or distribution account.
When personal purchases and rental expenses come from the same bank account, bookkeeping becomes more complicated.
You may struggle to identify which transactions belong to the rental property.
Better approach: Maintain separate business bank accounts where practical and document any personal funds used for rental purposes.
If you pay a legitimate rental expense using personal funds but never record it, your accounting reports may understate the property's expenses.
This can make your rental appear more profitable than it really is.
Better approach: Record the underlying expense and the appropriate owner contribution or reimbursement liability.
Not every transfer from an owner to the rental business is a capital contribution.
Sometimes an owner lends money to the business with the expectation of repayment.
These transactions may need to be recorded as loans payable rather than owner equity.
Better approach: Clearly document whether funds represent capital contributions, reimbursable expenses, or formal loans.
Properly recording owner contributions and withdrawals provides several benefits.
More accurate profitability reports. Separating owner transactions from rental operations helps you understand how much income your property actually generates.
Better cash flow visibility. You can distinguish money earned by the property from money added or withdrawn by the owner.
Cleaner tax records. Correct categorization helps prevent owner transfers from being confused with taxable rental income or deductible operating expenses. The tax treatment of contributions and distributions depends on the ownership structure.
Easier financial planning. Understanding how much personal money you've invested into your rental operations can help you evaluate future funding needs.
Improved portfolio management. When you own multiple rental properties, tracking owner-funded transactions by property can help you identify which investments require additional financial support.
Tracking rental property finances manually can become challenging, especially when you're managing multiple properties, bank accounts, and transactions.
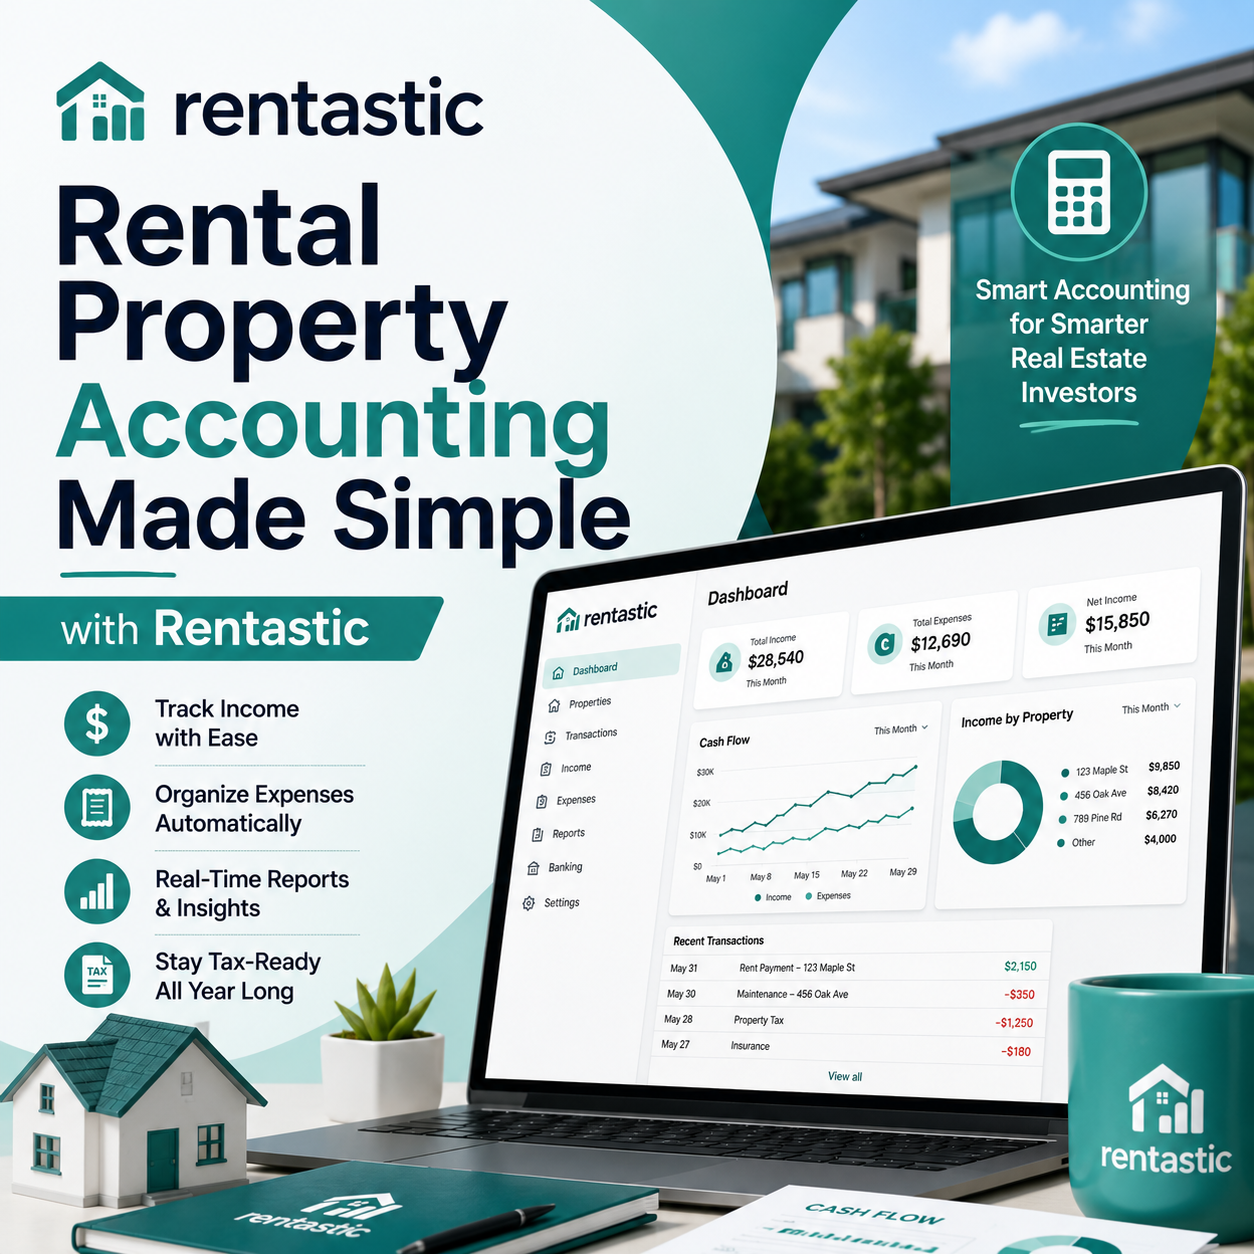
Rentastic helps landlords organize their rental income, expenses, and financial records in one place.
With Rentastic, you can:
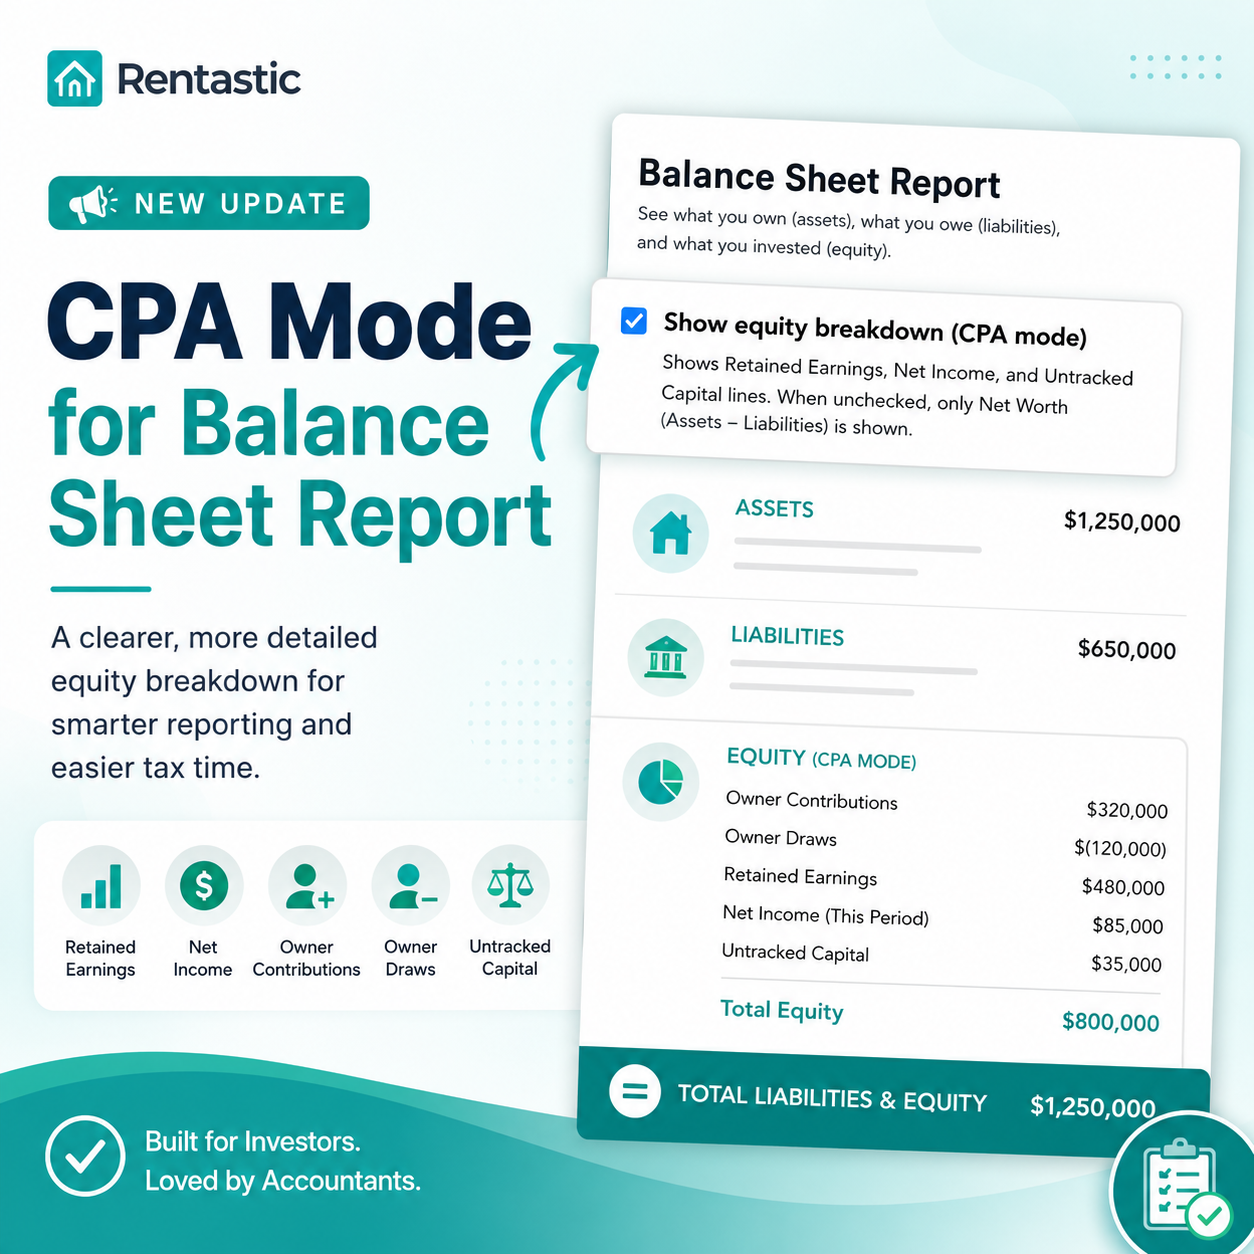
For owner contributions and withdrawals, use appropriately configured categories and review how those transactions appear in your reports. Rentastic's transaction tracking can help organize these activities, but it should not be assumed to replace a full double-entry equity ledger.
By maintaining clear records, you can avoid mixing personal cash movements with actual rental property performance.
To keep your rental property accounting accurate, develop a consistent process for recording owner-related transactions.
A consistent bookkeeping process can prevent small categorization mistakes from turning into larger financial reporting problems.
Owner contributions and withdrawals are normal parts of managing rental property finances, but they should never be confused with the income and expenses generated by your investments.
Owner contributions add funds to your rental business, while owner withdrawals remove funds for personal use. Neither is automatically rental income or an operating expense.
By recording these transactions correctly, you can maintain more accurate financial reports, better understand your property's cash flow, and make smarter investment decisions.
Whether you own one rental property or manage an expanding portfolio, keeping owner transactions separate is an important step toward cleaner, more reliable bookkeeping.
Take control of your rental property finances with Rentastic.
Organize your transactions, monitor rental performance, and simplify your bookkeeping.
RECENT POSTS


© 2025 Rentastic
Rentastic is registered as a trademark. Terms and conditions, features, support, pricing, and service options subject to change without notice.



















Comments